What’s Changing With Colorado Homeowners Insurance After Hail Storms
If you’ve filed a hail claim in Colorado Springs recently and been surprised by how much you owed before your insurer paid a dollar, you’re not imagining things. Most major carriers in Colorado have moved away from flat-dollar hail deductibles and onto a percentage of your home’s insured value, and on a $400,000 home, a 2% deductible means $8,000 out of pocket before coverage kicks in. Here’s what’s actually changed, and what it means the next time hail comes through the Front Range.
What Is a Percentage-Based Hail Deductible?
A percentage-based deductible calculates what you owe as a share of your home’s insured value instead of a flat number like $1,000 or $2,500. Common percentages in Colorado run 1% to 5%, and the math adds up fast. On a $500,000 home, a 2% wind and hail deductible comes to $10,000, due before your insurance company contributes anything toward the repair. If your declarations page lists a percentage instead of a dollar amount next to “wind/hail,” that’s the deductible you’re working with.
Why Insurers Are Moving Away From Flat-Dollar Deductibles
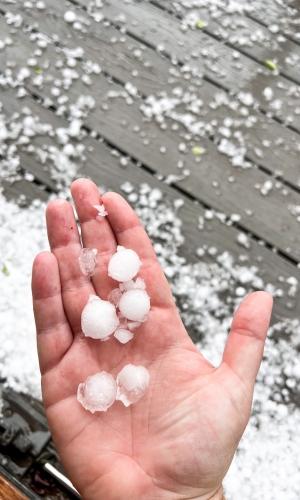
Colorado sits in what the insurance industry calls Hail Alley, and the losses have been significant enough that carriers have restructured how they price roof risk rather than continue raising premiums alone. Hail now accounts for roughly 26% to 54% of a typical Colorado homeowners premium depending on the county, according to a Colorado Division of Insurance analysis. Along the Front Range specifically, hail makes up close to half of what homeowners pay every year. Percentage deductibles, roof payment schedules, and cosmetic damage exclusions are how insurers have shifted more of that cost back onto policyholders.
What Colorado’s SB-38 Law Means for Your Roofing Contract
Colorado Senate Bill 38, in place since 2012, protects homeowners during the claims process and puts real limits on what a roofing contractor can offer you. Under SB-38, it’s illegal for a roofing company to pay, waive, or rebate any part of your insurance deductible, and any contractor who tries is putting your claim at risk, since your insurer isn’t obligated to honor an estimate tied to a waived deductible. The law also requires a written, signed contract before work begins, which should spell out the scope of work, your cancellation rights, and a clear statement about the deductible itself. The Colorado Roofing Association’s consumer fact sheet breaks down the full list of contract requirements if you want to see exactly what your contractor is required to disclose.
How Pierce Roofing Helps You Navigate a Hail Claim
We inspect your roof after a storm, document the damage in detail, and walk you through what your policy actually covers before you file anything. Because we handle insurance claims for Colorado Springs homeowners regularly, we can tell you early on whether your damage is likely to clear your deductible and what to expect from the adjuster process. If your current roof is nearing the end of its life, it’s also worth asking about Class 4 impact-resistant shingles, since many Colorado insurers offer premium discounts for homes with Class 4 roofing, which can help offset some of what a higher percentage deductible costs you over time.
Frequently Asked Questions
If you’re not sure whether your roof has hail damage or what your policy actually covers, schedule a free inspection and we’ll walk you through it.